Archive

October 16, 2026

Browsing

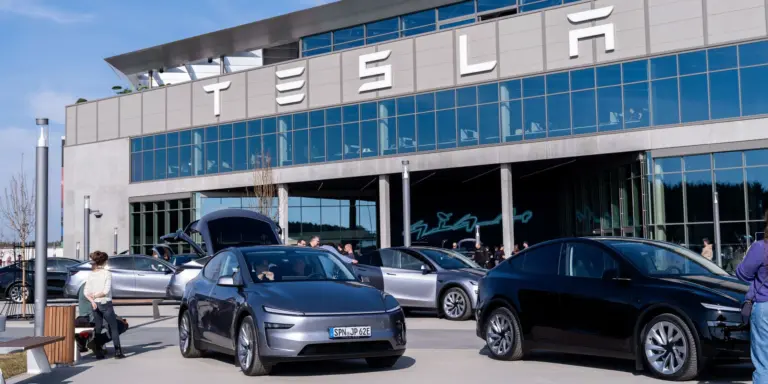
Tesla TSLA shares fell close to 2% on Thursday, extending their losing streak to four sessions as a broader technology sell-off and speculation about a potential merger with SpaceX weighed on investor sentiment.

The electric vehicle maker’s shares have declined around 18% this year, with investors assessing the company’s ambitious artificial intelligence plans, upcoming product announcements and the possibility of a major corporate restructuring under CEO Elon Musk.

Attention has now turned to the prospect of Tesla combining with SpaceX, a move that could bring Musk’s automotive, space and AI ambitions closer together.

SpaceX-Tesla merger could be announced in december

Barclays analyst Dan Levy said Thursday that a merger between Tesla and SpaceX could be announced before Tesla’s annual meeting on December 6.

According to Levy, such a transaction would represent another step in Musk’s broader artificial intelligence ambitions. SpaceX is expected to be the likely acquirer, with the deal potentially structured as an all-stock transaction in which Tesla shareholders receive shares in SpaceX.

Based on the current valuations, SpaceX has a market capitalization of around $2.1 trillion, compared with approximately $1.5 trillion for Tesla.

Musk would own about 37% of the combined company under a transaction based on those valuations, while retaining roughly 57% of its voting power, according to Barclays.

Musk has recently hinted at the possibility of combining the businesses, saying that Tesla overlaps “on so many fronts with SpaceX.”

A merger could bring together Tesla’s electric vehicles and robotics operations with SpaceX’s space technology and the companies’ wider AI ambitions.

Tesla’s Roadster reveal in focus

Tesla is also preparing to unveil its long-promised Roadster sports car on Thursday at a SpaceX test facility in Texas.

The company is expected to demonstrate a version of the vehicle capable of flying, adding to the anticipation surrounding the long-delayed model.

Musk previously described the planned debut as an event that “might be one of the most spectacular demos ever.”

Despite the attention surrounding the announcement, questions remain about the Roadster’s potential commercial impact and whether the launch can materially change investor expectations for Tesla.

Andrew Rocco, a stock strategist at Zacks Investment Research, said the product could generate considerable excitement but may not significantly affect the company’s financial performance.

“It’s going to be an exciting product. Likely, it’s going to build a lot of hype, but I don’t think that it’s going to be a needle mover,” Rocco told Bloomberg. “Musk loves to build hype around the brand.”

The upcoming reveal therefore represents another test of Tesla’s ability to translate product announcements and ambitious demonstrations into sustained investor confidence.

Broader tech sell-off adds pressure

Tesla’s decline also came against a difficult backdrop for technology stocks, as concerns about AI spending and financing costs weighed on companies associated with the industry.

Investors have been reassessing the scale of investment required to build AI infrastructure and whether those commitments can generate sufficient returns, adding pressure to valuations across parts of the technology sector.

The Philadelphia Semiconductor Index declined for a seventh consecutive session with the Nasdaq composite also in red.

The broader macroeconomic environment has added to the uncertainty. US wholesale inflation accelerated in September to its highest level since 2022, raising concerns that price pressures could persist and limit the Federal Reserve’s room to ease monetary policy.

Earlier in the day, UBS projected another Federal Reserve rate increase in March 2027, extending its forecast for the central bank’s tightening cycle.

Higher interest rates can weigh on equity valuations by increasing borrowing costs and making bonds more attractive relative to stocks. The prospect of prolonged monetary tightening has therefore added another source of pressure for growth-oriented companies.

The post Why Tesla is falling ahead of Roadster sports car launch? appeared first on Invezz
ServiceNow shares NOW rose 6.2% in trading on Thursday after TD Cowen raised its price target on the enterprise software company to $165 from $140 and reiterated its Buy rating.

Analyst Derrick Wood expects a strong third-quarter performance, supported by customer upgrades, growth in security products and demand from US federal agencies.

The gains came as investors rotated into enterprise software stocks amid a broader sell-off in semiconductor shares and concerns about heavily indebted artificial intelligence companies.

The shift lifted several software names, with Salesforce gaining almost 4%, Adobe rising more than 3% and Oracle climbing 2.8%.

The iShares Expanded Tech-Software Sector ETF (IGV) added about 1.05%, while the VanEck Semiconductor ETF (SMH) fell 2.11%, heading for its eighth consecutive losing session.

Investors rotate into enterprise software

The sector’s relative strength came as fresh inflation data reinforced concerns that prices and borrowing costs could remain elevated for longer.

US producer prices rose 1.3% in September from the previous month, more than double economists’ forecast of 0.5%, according to the Bureau of Labor Statistics.

Annual producer price inflation reached 6.3%, against expectations of 5.3%, marking the largest increase since December 2022.

Core producer prices, which exclude food and energy, increased 0.7% month over month and 5% year over year.

The consumer price index released on Wednesday also came in hotter than expected, with headline inflation reaching 3.7%, compared with forecasts of 3.6%.

Against this backdrop, investors appeared to favour established enterprise software businesses as concerns about debt exposure weighed on AI-related companies.

ServiceNow offers exposure to enterprise AI through its software products, while TD Cowen’s analysis points to its comparatively modest debt burden.

TD Cowen expects strong third-quarter results

Wood’s channel checks indicate that customers are upgrading to ServiceNow’s IT service management (ITSM) Prime tier and purchasing more of its other core products.

He also expects the company’s Armis security business and US federal operations to outperform expectations.

TD Cowen sees scope for a modest acceleration in growth in current remaining performance obligations (cRPO), which measure contracted revenue expected to be recognised over the next 12 months.

According to Wood, one partner reported that around half of renewal discussions now result in AI upgrades, typically to Prime.

These upgrades can increase average selling prices by roughly 30%, providing another potential source of revenue growth.

ServiceNow is scheduled to report its third-quarter results on October 28.

The earnings release will offer investors an opportunity to assess whether the anticipated improvement in cRPO growth is materialising.

Wood also sees the company’s stronger security positioning and growth in AI-related contracts as potential supports for further valuation gains.

Valuation and debt remain in focus

ServiceNow shares have gained more than 55% since the company reported its second-quarter results.

TD Cowen’s revised $165 price target is based on approximately 24 times enterprise value to projected 2027 free cash flow, compared with around 20 times at current prices.

The analysis also places the stock’s valuation at roughly 40% below its five-year average of about 40 times next-twelve-month free cash flow.

The firm estimates ServiceNow’s net debt at approximately $3.8 billion, against a market value of $144.7 billion.

Its annual contract value tied to AI has also surpassed $1 billion, according to TD Cowen.

However, the analyst’s identified risks include ServiceNow’s dependence on IT service management and its reliance on large, multimillion-dollar deals.

The post ServiceNow stock rises 6% as investors rotate to enterprise software stocks appeared first on Invezz

Anthropic reported third-quarter revenue of $16.8 billion as growth slowed from the previous quarter, raising questions about its planned IPO valuation.

US wholesale inflation accelerated to 6.3% annually in September, strengthening concerns about persistent price pressures and the Federal Reserve’s interest rate outlook.

CoreWeave shares rebounded as BNP Paribas highlighted the risks associated with its financing structure, while gold prices climbed as a weaker dollar and lower Treasury yields supported the precious metal.

Anthropic’s revenue growth slows ahead of IPO

Anthropic’s revenue rose 45% quarter over quarter to $16.8 billion in the third quarter, while the Claude developer told prospective investors it was profitable on an adjusted basis.

However, the growth rate slowed compared with earlier quarters.

Revenue increased from approximately $4.7 billion in the first quarter to $11.6 billion in the second, representing growth of well over 100% before the latest advance.

The company is targeting a valuation above $2 trillion, while analysts who met executives estimate its annual revenue run rate could reach around $110 billion by year-end.

However, uncertainty remains over whether its reported revenue reflects gross or net sales, given its cloud partnerships.

Anthropic’s challenge will be sustaining revenue growth as models become cheaper and competition intensifies.

US wholesale inflation accelerates to 6.3%

US producer prices rose 1.3% month over month and 6.3% year over year in September, according to the Bureau of Labor Statistics.

Both readings exceeded economists’ expectations of 0.6% monthly growth and 5.5% annually. The annual increase was the largest since December 2022.

Goods prices surged 2.6%, their largest monthly increase since the series began in December 2009. Energy prices jumped 10.8%, accounting for more than 80% of the increase in goods costs, while gasoline prices climbed 20.3%. Food prices rose 1.2%.

Services prices increased 0.8% after advancing 0.2% in August. Trade services margins rose 1.4%, contributing nearly half of the increase in services prices.

The report followed September’s hotter-than-expected consumer inflation figures.

Initial jobless claims, meanwhile, edged up by 1,000 to 199,000 in the week ended October 10, remaining below economists’ forecast of 200,000.

The data strengthened expectations that the Federal Reserve could keep rates higher for longer. Traders assigned roughly a 27% probability to an October rate hike, according to CME FedWatch data, while markets priced in an 89.5% probability of an increase in December.

CoreWeave shares rebound even as financing risks remain

CoreWeave shares rose nearly 5% on Thursday, recovering from earlier losses as bond yields rebounded from earlier levels and BNP Paribas assessed the company’s financing structure.

Analyst Daniel Wang maintained an Overweight rating and a $169 price target, distinguishing between CoreWeave’s AssetCo and ParentCo debt structures.

Wang said AssetCo obligations appeared to carry relatively limited principal repayment risk because underlying cash flows were expected to exceed debt obligations as assets reached full revenue capacity.

Those cash flows would cover operating expenses, interest and principal repayments, with remaining free cash flow potentially available to ParentCo.

However, Wang identified ParentCo leverage and the company’s continued reliance on external financing to expand capacity as the more pressing concerns.

He said some unsecured obligations had implied yields as high as 15%, potentially making traditional ParentCo debt financing increasingly uneconomic.

Convertible debt and equity issuance could therefore become the primary sources of additional corporate capital until credit investors gain confidence in CoreWeave’s ability to fund itself.

Wang said stronger free cash flow from active capacity and newer contracts could help, but the stock remains increasingly sensitive to credit-market sentiment.

Gold rises as dollar and Treasury yields fall

Gold prices climbed on Thursday, recovering from a one-week low as the US dollar weakened and Treasury yields declined, despite the latest inflation data.

Spot gold rose 1.66% to $4,173.2 an ounce, while US December gold futures settled 2.1% higher at $4,194.2.

The dollar index fell 0.5%, and the benchmark 10-year Treasury yield reached a three-week low, supporting demand for the non-yielding metal.

Investors awaited comments from Fed Chair Kevin Warsh at the International Monetary Fund’s annual meeting.

Other precious metals also advanced. Spot silver gained 2.5% to $57.05 an ounce, platinum rose 1% to $1,622.40, and palladium climbed 3.4% to $1,131.25.

The post Evening digest: Anthropic revenue growth slows, US PPI rises appeared first on Invezz

US stocks ended mostly higher on Thursday as investors shifted away from some artificial intelligence-related stocks and into healthcare, consumer, and other defensive sectors amid concerns about elevated borrowing costs and persistent inflation.

The Dow Jones Industrial Average gained 556 points, or 1.08%, while the S&P 500 rose 0.33%.

The Nasdaq Composite added 0.08% as weakness in semiconductor stocks limited gains in technology shares.

Investors assessed September producer price data showing the strongest annual wholesale inflation increase since December 2022.

The figures followed hotter-than-expected consumer inflation data released on Wednesday, strengthening concerns that the Federal Reserve could raise interest rates again before the end of the year.

Dow leads gains as investors favour defensive stocks

Healthcare and consumer companies supported the broader market, with Eli Lilly, UnitedHealth and Walmart gaining following rating upgrades from Deutsche Bank.

Walmart shares climbed nearly 2%, while Nike advanced more than 5%.

The gains reflected a shift towards companies outside the technology sector as investors reassessed the risks associated with expensive AI infrastructure investments and higher financing costs.

The S&P 500 remains up approximately 13% in 2026 after reaching a record high last week, with much of its advance driven by AI-related stocks.

However, the index was trading at around 19 times expected earnings, its lowest valuation level since 2023, according to the supplied report.

The change in market leadership came as Treasury yields remained near multiyear highs despite retreating on Thursday.

The 10-year Treasury yield has been a focus for investors concerned that persistent inflation and elevated oil prices could keep borrowing costs high.

Higher financing costs could affect businesses across the economy, including companies investing heavily in data centres and AI infrastructure.

Semiconductor stocks extend losses amid AI concerns

Technology stocks remained under pressure as investors scrutinised AI companies with substantial debt obligations and questioned whether the sector’s growth expectations were sustainable.

The Philadelphia Semiconductor Index fell for a seventh consecutive session.

Broadcom and Nvidia declined after Taiwan Semiconductor Manufacturing Company (TSMC) expressed caution about its outlook for 2027, despite reporting a sixth consecutive quarter of record profits supported by AI demand.

Dell Technologies and Hewlett Packard Enterprise also remained under pressure following the previous session’s losses linked to concerns about borrowing costs.

Memory-related stocks faced additional headwinds from worries about a potential supply glut and increasing competition from China.

Seagate Technology, Western Digital and SK Hynix extended their declines during the week.

Anthropic’s latest revenue figures added to questions about the pace of AI growth.

The Claude developer generated $16.8 billion in third-quarter revenue, although the increase from the previous quarter was slower than its earlier expansion.

Not all AI-related stocks declined.

CoreWeave gained around 3%, recovering from a fall of more than 15% in the previous session, while Micron Technology rebounded from earlier losses to finish nearly 1% higher.

Inflation data raises Fed rate hike expectations

US producer prices rose 1.3% month over month and 6.3% year over year in September, marking the largest annual increase since December 2022.

The figures exceeded economists’ expectations and indicated that inflationary pressures were spreading across goods and services.

The report followed September consumer price data that also came in hotter than expected, increasing concerns that the Federal Reserve might need to tighten monetary policy further.

According to CME FedWatch data, traders priced in a 67% probability of a rate increase by the Fed’s December meeting, up from 62% on Wednesday.

Elsewhere, Rocket Lab shares fell after the company delayed the first launch of its larger Neutron rocket until next year. FMC also tumbled after sharply reducing its third-quarter outlook.

The post Dow rises 556 points as investors rotate out of AI stocks on inflation fears appeared first on Invezz

Top real estate companies are rallying today. Zillow Group stock jumped 11%, while Better Home & Finance and Opendoor surged 33% and 17%, respectively. Other major names, including UWM Holdings and PennyMac Holdings, also traded in the green.

Zillow Group, Better Home, and Opendoor jumped as bond yields fell

While these stocks jumped, they remain well below their highs for the year. Zillow has dropped by 62%, while Better Home & Finance and Opendoor have slumped by 85% and 72% in the last 12 months. 

The rebound coincided with the retreat in bond yields. Data show that the ten-year yield dropped to 5.06%, while the five-year fell to 4.86%. The two have dropped substantially from their highest points this month. 

US bond yields dropped even after the US published strong consumer inflation data. The report showed that the headline Consumer Price Index (CPI) jumped to 3.7% last month. Core inflation rose 2.6% in September. Another report released today showed that the producer price index (PPI) rose from 0.5% in August to 1.3% in September, higher than the expected 0.6%. 

Despite these numbers, market participants don’t expect the bank to hike interest rates this month. Odds of the bank leaving interest rates unchanged moved to 72%. Most analysts expect the bank to hike interest rates by 0.25% in the December meeting. 

The falling bond yields have led to a brief retreat in mortgage rates. The average mortgage rate dropped slightly to 7.3%. Despite this, these rates have remained at the highest level in nearly three years. 

Lower mortgage rates would boost companies like Zillow Group, Opendoor, and Better Home & Finance. Indeed, the rising mortgage rates explain why these stocks have plunged by double digits this year. 

Mortgage rates have impacted these companies

The soaring mortgage rates explain why these stocks have been under pressure this year. Zillow, the biggest portal, has suffered substantially this year as demand for homes has done. SimilarWeb data shows that its website traffic dropped by 11% in September to 317 million. 

Its recent results showed that its revenue rose by 18% to $772 million, while its net loss jumped to $4 million. Analysts expect the upcoming results to show that its revenue rose 11% to $754 million, a sign that its business is slowing.

Opendoor’s business has been one of the most pressured companies because of the rising mortgage rates. In a recent statement, the company’s CEO clarified that the company was not near its breakeven point. She said: 

“The worsening housing market at the end of August pushed us roughly six to eight weeks behind on our Adjusted EBITDA guidepost, meaning the twelve-month window in which we expect to be adjusted EBITDA profitable now starts this quarter rather than last quarter.”

Better Home & Finance has also come under pressure as higher interest rates have led to a dip in originations. While its second quarter had strong growth, the estimate is that its revenue will grow by 12% to $50 million. Looking forward, these stocks will remain under pressure once the ongoing dip-buying ends.

The post Here’s why Zillow Group, Better Home, and Opendoor stocks are rising today appeared first on Invezz

Owning gold and silver has long been seen as a strategy for stability and wealth preservation, but actually using those assets to buy a cup of coffee or pay for groceries has traditionally been a cumbersome process. That changes today with the introduction of the OneGold Card. Developed by the vaulted metals platform in partnership with Mastercard, this new payment tool allows users to spend their precious metal holdings instantly at any retailer that accepts the network, effectively turning physical bullion into a liquid spending account.

The technology works by automating the liquidation process behind the scenes. When a user swipes their card or uses a digital wallet like Apple Pay or Google Pay, the platform calculates the necessary amount of gold or silver needed to cover the cost and converts that fraction of their holding into currency at current spot prices. This eliminates the old school headache of visiting coin shops, waiting for checks to clear, or dealing with slow bank transfers just to access one’s own investments.

To encourage adoption, OneGold is waiving selling fees on U.S. gold conversions used for these transactions, with a similar fee waiver extending to silver holders through late 2026. Ken Lewis, CEO of Bullion International Group, noted that this move essentially makes gold functional as money once again. By removing the barriers between storing value and spending it, the company aims to give investors the safety of physical ownership combined with the convenience of modern banking.

This launch coincides with a comprehensive overhaul of OneGold’s mobile app and website to streamline the user experience. Since its founding in 2018, OneGold has positioned itself as a middle ground between high-cost physical storage and abstract exchange traded funds. With over four million ounces of metal currently managed under insurance from Lloyd’s of London, the firm provides clients with audited ownership of physical assets stored in global vaults while now offering them unprecedented ease of access via their wallets.

SSR Mining is significantly scaling up its presence in the American West through an all-cash acquisition of Roxmore Resources. The move focuses primarily on the Converse gold project, which sits just six kilometers away from the existing Marigold Complex along Nevada’s prolific Battle Mountain-Eureka Trend. By absorbing this neighboring asset, SSR Mining secures a massive resource consisting of millions of ounces of gold while cementing its position as the third largest gold producer currently operating within the United States.

Executive Chairman Rod Antal described the purchase as a compelling opportunity to secure a high quality resource at an attractive price point. Because the two sites are so close together, the company believes it can eliminate redundant administrative roles and overhead costs, leading to estimated savings of at least 200 million dollars over the life of the mine. This strategic alignment makes SSR Mining what leadership calls the natural acquirer for such a deposit, allowing them to leverage shared infrastructure and operational efficiencies across their Nevada holdings.

Looking ahead to production, the Converse project is expected to contribute between 150,000 and 170,000 ounces of gold per year starting around 2033. While initial construction is estimated to cost nearly 900 million dollars, those expenditures aren’t expected until the early 2030s. When combined with other major operations like Cripple Creek and Victor in Colorado, SSR Mining anticipates its total U.S. output will average up to 400,000 ounces annually over a decade starting in 2033, with some peak years potentially climbing even higher.

To fund this expansion without taking on new debt, SSR Mining is utilizing its own balance sheet, supported by recent divestments designed to shift its focus toward the Americas. Earlier this year, the firm generated substantial liquidity by selling most of its interest in Turkey’s Copler gold mine for 1.5 billion dollars. As part of this transition, non core exploration properties previously held by Roxmore will be spun off into a separate entity funded with 10 million dollars in cash and shared between both companies’ stakeholders.

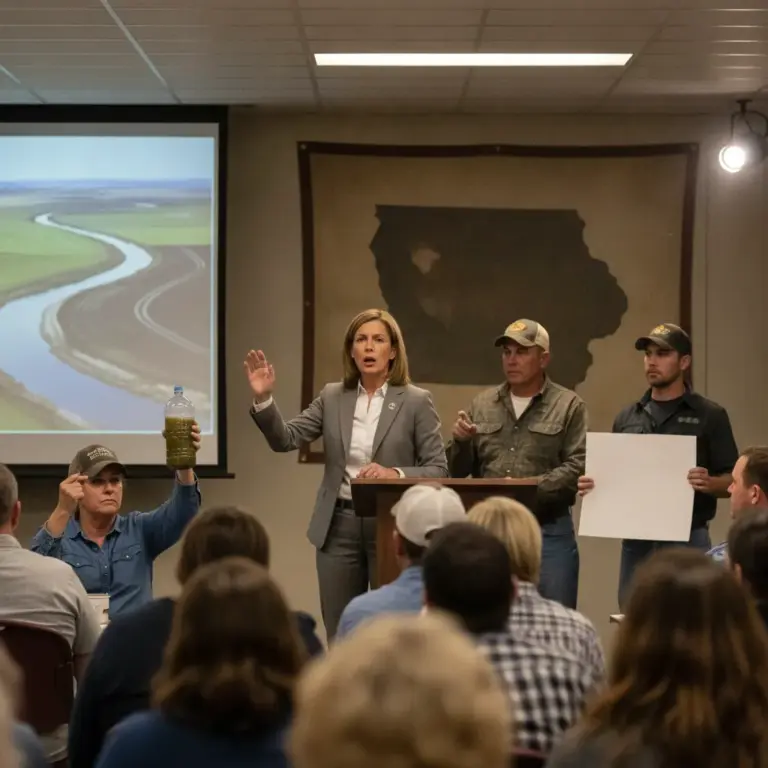
For decades, talking about water quality in Iowa was considered a political third rail. To question the runoff of chemical fertilizers and animal waste meant risking a confrontation with the state’s powerhouse agricultural industry, a move few politicians were willing to make. But as the midterms approach, that silence has broken. From rural town halls to urban debates, candidates across the spectrum are finally grappling with a simmering crisis involving contaminated waterways and some of the highest cancer rates in the United States.

The tension is rooted in a geographic divide between conservative farming communities and liberal urban centers. While many farmers have adopted voluntary measures to curb runoff, critics argue that without strict regulation, downstream residents are left footing the bill for pollution. This frustration has reached a boiling point following repeated water usage restrictions in Des Moines and a rising grassroots health movement in small towns focused on cleaning up the food and water supply. With Iowa ranking second in the nation for new cancer diagnoses, voters are increasingly asking whether the chemicals used on their fields are ending up in their taps.

Democratic candidate Josh Turek has leaned directly into this anxiety, arguing that every citizen deserves clean water free from carcinogenic risks. On the other side, Republican Congresswoman Ashley Hinson maintains that while challenges exist, current federal regulations ensure tap water remains safe. Even within her own party, however, cracks are appearing. Gubernatorial hopeful Zach Lahn has diverged from traditional GOP rhetoric by explicitly linking agrochemicals to the state’s cancer surge, admitting that tests of his own rural well water showed nitrate levels far exceeding federal limits.

Despite these heated exchanges, there is a cautious consensus among leadership that something must change. Governor Kim Reynolds recently committed hundreds of millions of dollars toward water infrastructure and conservation incentives, insisting that safety is non-negotiable regardless of politics. Yet for many Iowans watching their neighbors fall ill or seeing their utilities struggle to filter out nitrates daily, financial investment may not be enough. What was once a taboo conversation has become a central pillar of the campaign trail, turning Iowa’s environment into a referendum on public health.

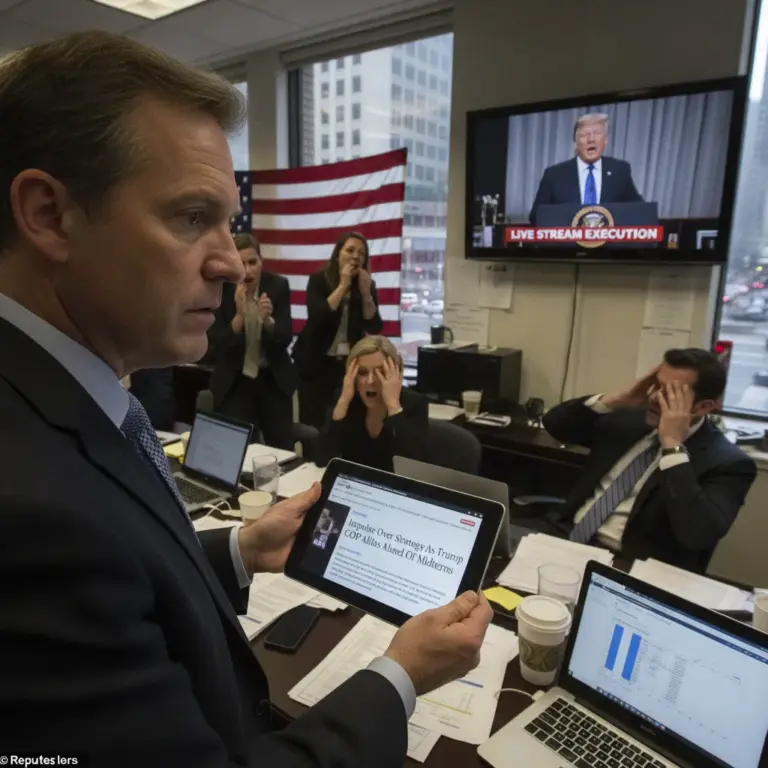
As the 2026 midterm elections approach, a growing number of Republican candidates find themselves wishing they could distance their campaigns from President Donald Trump. This desire stems not just from the president’s current standing in the polls, but from a pattern of erratic decision making that suggests his political instincts are operating in a vacuum. From proposing the use of taxpayer funds for personal campaign advertisements to suggesting the live streaming of an execution, the administration has repeatedly pushed boundaries that alienate a vast majority of the American electorate.

The volatility became particularly evident with the plan to broadcast the execution of Fort Hood shooter Nidal Hasan. Only after a series of devastating polls revealed that eighty percent of voters found the idea abhorrent did the White House abruptly backtrack. Similar patterns emerged regarding proposed taxpayer funded ads, which saw overwhelming opposition across various demographics. These episodes highlight a troubling lack of internal pushback within the administration, suggesting that advisors are either unable or unwilling to steer the president away from ideas that appear politically suicidal during an election cycle.

Beyond these specific controversies, Trump continues to champion positions that clash harshly with public sentiment during his rally appearances. Recent stops in Arizona and Montana saw him doubling down on aggressive trade wars with Canada and reviving long discarded fantasies about annexing foreign territories like Greenland. While he frames these moves as strength, polling indicates that most Americans view them as unnecessary provocations. His insistence that high oil prices and steep tariffs are benefiting the average citizen further disconnects him from a public currently struggling with rising costs and inflation markers hitting multiyear highs.

For observers who once searched for a hidden strategic genius behind Trump’s unpredictability, these latest maneuvers suggest something simpler: raw impulse and unchecked hubris. By ignoring economic reality and dismissing widespread disapproval until forced by polling data to pivot, Trump risks leaving GOP candidates adrift. Rather than providing a cohesive vision for victory in 2026, his current trajectory reflects a leader more interested in personal whims than electoral viability, potentially handing opponents a roadmap to success through sheer self sabotage.

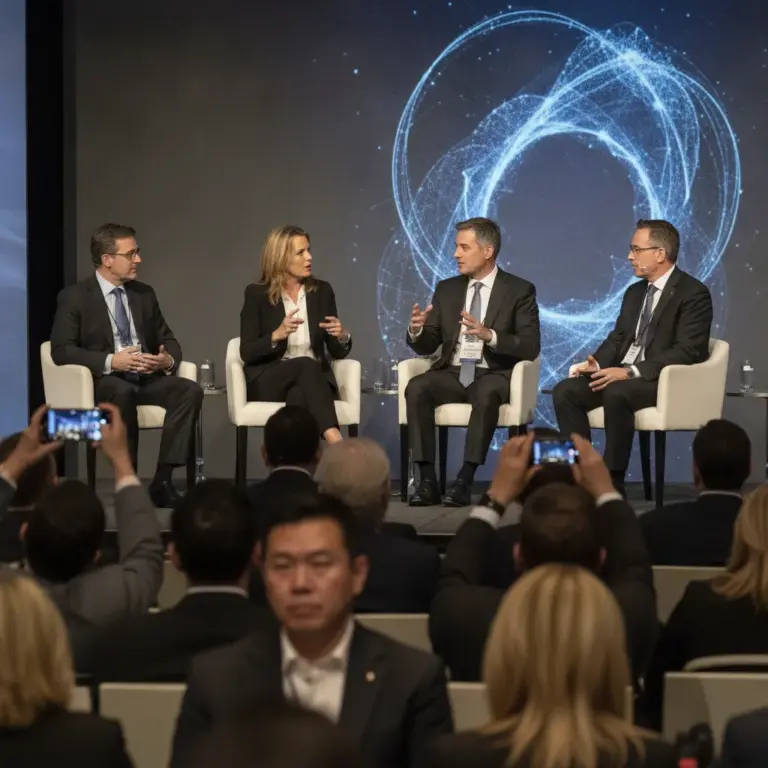
Despite the relentless hype surrounding generative artificial intelligence, few major organizations have actually redesigned their fundamental operations to center on the technology. During a recent Fortune Brainstorm AI event, four top executives argued that while companies are adopting AI at scale, they are mostly using it for peripheral tasks like drafting emails or summarizing meetings rather than reimagining how their businesses function. Marc Warner, the global chief technology officer at Accenture, noted that the number of enterprises that have truly reinvented their core processes is essentially close to zero.

The panel suggested that the primary barrier to success is not the software itself, but internal corporate culture. Warner described these efforts as politics projects rather than technical ones, noting that shifting the economic engine of an industry requires taking risks with core workflows that most leaders avoid. Greg Ulrich of Mastercard echoed this sentiment, explaining that simply speeding up one part of a lengthy manual process often creates bottlenecks elsewhere. True gains require remapping entire lifecycles and shrinking team structures, a feat that demands intense executive sponsorship and a willingness to disrupt established hierarchies.

This transition period has created a precarious environment where accountability remains murky and tools become obsolete almost instantly. When discussing what happens when an AI agent fails, Warner urged companies to abandon the blame game and instead encourage experimentation, provided there isn’t a catastrophic security breach. This need for agility is underscored by the sheer speed of innovation; Ulrich admitted that some of his firm’s custom AI tools from just a year ago already feel quaint and useless, forcing constant cycles of rebuilding.

As firms look toward the end of the decade, the strategy is shifting from broad enthusiasm to targeted value creation. For instance, AXA has moved away from hundreds of small test cases to focus on high-value goals involving billions of unstructured documents. While energy constraints may eventually slow progress in the early 2030s, these leaders agree that for now, the real challenge lies in bringing people along for the ride and overcoming the institutional inertia that keeps AI on the sidelines.