Archive

October 9, 2026

Browsing

PepsiCo shares PEP rose more than 1% on Thursday after the company reported quarterly revenue and earnings above Wall Street expectations, although the beverage and snacks giant lowered its full-year core profit forecast.

Revenue for the quarter rose 5.6% to $25.27 billion, beating analysts’ estimate of $24.96 billion, according to LSEG data.

Core earnings per share came in at $2.34, above the $2.29 expected.

The stronger quarterly results were overshadowed by a weaker outlook.

PepsiCo now expects fiscal 2026 core earnings per share, adjusted for currency fluctuations, to increase 1% to 2%, compared with its previous forecast for growth of 4% to 6%.

The company maintained a more optimistic view on revenue, expecting annual organic revenue to rise about 3%, compared with its previous forecast of 2% to 4%.

North America remains a key challenge

PepsiCo said its efforts to restore growth and profitability in North America are taking longer than expected, prompting the company to pursue additional structural cost reductions.

“In North America, we remain committed to improving growth and core ⁠operating margin. However, it is taking more time than we planned,” said PepsiCo CFO Steve Schmitt in prepared remarks.

“Looking ahead, we remain focused on building upon the strength of the International business while acting with urgency to sustainably improve our performance in North America through more investments in innovation, effective brand building, and sharper marketplace execution by channel,” said CEO Ramon Laguarta in a statement.

“Additional structural cost reduction actions are being identified and will be implemented in the coming months to help fund investments that aim to accelerate organic revenue growth and mitigate the impacts of rising input cost inflation,” he said.

The company’s North American food business saw volumes remain flat in the third quarter ended September 5, while beverage volumes fell 2% from a year earlier.

PepsiCo had already cut prices by as much as 15% on products including Lay’s and Doritos in February as it attempted to address affordability concerns.

Last month, it said it would raise prices on some US products to offset rising costs and improve profitability.

Activist pressure weighs on PepsiCo

The weakness has also kept pressure on PepsiCo to revive its soda business, improve its share price and consider changes to its portfolio following activist investor Elliott Investment Management’s disclosure of a roughly $4 billion stake last year.

After discussions with Elliott, PepsiCo said in December it would review its North American supply chain and pursue aggressive cost-cutting measures.

The stock has fallen 13% this year and 20% over the past six months.

Shares closed at $123.73 on Wednesday.

JPMorgan downgraded PepsiCo to Neutral from Overweight last month and cut its price target to $138 from $170.

Deutsche Bank also lowered its rating to Hold from Buy and reduced its target to $138 from $155.

The latest results could offer some relief, but the lower profit outlook suggests investors may remain focused on whether PepsiCo can accelerate its North American turnaround while controlling rising costs.

The post PepsiCo stock rises on earnings beat even as it lowers full-year profit forecast appeared first on Invezz
Intel and AMD shares traded lower on Thursday as a broader selloff in US equities intensified, with surging oil prices and Treasury yields raising concerns about inflation and interest rates.

Intel stock INTC fell about 6%, while AMD declined over 4%.

The Philadelphia Semiconductor Index was down over 3.8%.

Brent crude futures jumped 4.2% to above $104 a barrel amid persistent concerns over Middle East supplies and disruptions to US production caused by a hurricane.

Meanwhile, the 10-year Treasury yield climbed to 5.3%, close to its highest level since 2002.

Higher oil prices can add to inflationary pressure and strengthen expectations for higher interest rates.

Rising bond yields can also weigh on high-growth technology companies because they increase the discount rate applied to future earnings.

Intel faces questions over Terafab and CPU share

Intel has also faced company-specific pressure this week after Elon Musk acknowledged that Taiwan Semiconductor Manufacturing Co. could potentially participate in his Texas-based Terafab chip project.

The comments contributed to a more than 5% decline in Intel shares across Monday and Tuesday.

However, Musk and Intel CEO Lip-Bu Tan subsequently sought to reassure investors about Intel’s role in the project.

Tan told Bloomberg ahead of an event in Tokyo that Intel’s involvement would continue.

Musk also responded on X to speculation that TSMC could take a larger role in the facility.

“No, we will build and run the fab. Let there be ZERO doubt about that. Maybe TSMC subleases part of the Terafab if they want, but nothing more than that,” Musk said.

AMD prepares for bigger AI chip demand

AMD, meanwhile, is preparing to substantially increase chip supply next year as it seeks to capitalize on growing demand for artificial intelligence infrastructure.

“We’ve been able to increase our supply as we’ve gone through 2026, and we’re going to substantially increase our supply in 2027,” CEO Lisa Su told reporters in Taipei.

AMD has been expanding its AI accelerator business as it competes with Nvidia, with the company’s market value recently surpassing $1 trillion.

The company could also benefit from rising demand for CPUs as AI workloads become more complex.

Agentic AI could boost CPU market

Meanwhile, earlier this week, Mizuho said the rise of agentic AI applications could significantly increase demand for CPUs, potentially benefiting chipmakers including AMD and Intel.

“We estimate agentic CPUs reaching ~$80B by 2030E (~123% 4Y CAGR), head-node CPUs to $68B (~61% 4Y CAGR), and traditional CPUs to $60B (~2% 4Y CAGR),” said Mizuho analysts, led by Vijay Rakesh, in an investor report.

“Total Server CPU TAM we estimate reaches ~$209B by 2030E (32% 4Y CAGR) and is conservatively below AMD’s AMD target of >$220B. Our bottom-up projection sees Agentic AI driving CPU, DRAM, and NAND growing to 22-30% of their respective total markets (number of bits shipped). Our model estimates Agentic AI CPU demand as a % of total server CPUs grows from ~4% today to ~30% by 2030E.”

The brokerage raised its price target on AMD to $705 from $580 and lifted its Intel target to $114 from $92.

It also raised targets on Dell, SanDisk and Super Micro Computer, maintaining an Outperform rating on all except Super Micro, which remained Neutral.

Mizuho identified four leading-edge processors for agentic AI workloads: Arm’s AGI CPU, AMD’s Venice, Nvidia’s Vera and Intel’s Diamond Rapids.

The outlook provides a longer-term counterweight to the immediate pressure facing semiconductor stocks.

The post Why are Intel and AMD stocks plunging on Thursday? appeared first on Invezz

OpenAI’s annualised revenue is approaching $50 billion, the Financial Times reported, citing financial documents shared with investors, falling about $20 billion short of previously reported figures.

The discrepancy could temper expectations around the pace of demand for artificial intelligence services as investors closely track revenue growth at OpenAI and rival Anthropic.

Annualised revenue figures have become an important measure of AI demand and are closely linked to the significant infrastructure spending supporting the sector.

OpenAI had recently told investors that its revenues were approaching $50 billion on an annualised basis at the end of September.

That compares with a $70 billion figure reported by the Financial Times and other media outlets late last month.

OpenAI and Anthropic use different revenue calculations

The difference in the figures stems from the way OpenAI and Anthropic calculate annualised revenue, according to the person familiar with the matter cited in the report.

Anthropic includes revenue generated through cloud partners such as Amazon Web Services and Google Cloud, while OpenAI does not include those sales in its calculation.

According to the person, attempts by OpenAI investors to “gross up” the company’s annualised revenue in order to make it directly comparable with Anthropic contributed to the differing figures.

Those efforts resulted in reports that OpenAI’s annualised revenue had reached $40 billion in August.

The company has since told investors that its revenues have grown more than 70%, which contributed to the subsequently reported $70 billion figure.

Bloomberg News reported in August that OpenAI’s revenue run rate had topped $40 billion.

OpenAI plans $30B funding round as IPO is delayed

The revenue figures come as OpenAI seeks fresh capital following its decision to push back plans for an initial public offering.

Bloomberg reported last week that the company aims to raise at least $30 billion in a new funding round.

OpenAI is seeking a valuation of around $1.4 trillion, excluding the money raised, according to people familiar with the matter.

OpenAI most recently raised $122 billion in March at a valuation of $852 billion, including the money raised.

The latest funding is intended to act as a bridge round and provide additional capital instead of an IPO, according to the report.

OpenAI and Anthropic are competing to attract business customers and increase revenue ahead of potential public listings.

Both companies have filed confidential paperwork to go public, while Anthropic could list its shares as soon as this fall.

OpenAI Chief Executive Officer Sam Altman recently said the company would not go public this year.

In an interview with Bloomberg TV, Altman said the company wanted to navigate heightened concerns around AI safety without the pressure associated with being a newly public company.

“We just want to get our feet under us,” Altman said, adding that he believes investors will be “patient” with OpenAI’s IPO planning.

OpenAI continues to expand AI products and subscriptions

Despite the revenue reporting discrepancy, OpenAI continues to expand its product offering and compete in the growing market for AI agents.

The company recently unveiled Dots, an always-on AI agent designed to compete with products such as Meta’s Muse.

OpenAI has also introduced a new $500 subscription tier with higher usage limits and faster processing speeds, while reducing some usage limits for its $200 plan.

The company has also sought to sharpen its product focus, with renewed momentum around tools designed to streamline coding and other work.

At the same time, OpenAI faces increasing scrutiny over the potential risks associated with advanced AI systems, including cybersecurity concerns.

The company has also been working through additional safety requirements as AI capabilities advance.

The post OpenAI revenue run rate falls short of $70B figure: report appeared first on Invezz

Apple is preparing to expand its presence in the smart home market, with the company set to unveil a new range of devices at an event in New York City next week.

Apple has announced an event for October 13 titled “Welcome Home”.

The event is expected to feature a new smart home hub with a screen, an updated HomePod mini, and a refreshed Apple TV set-top box, said a Bloomberg News report.

Apple could also introduce smart home products developed with LG Electronics, including a doorbell, cameras, a smart lock and a thermostat.

The expansion comes as Apple looks to revive its HomeKit smart home platform while using its Siri AI assistant to strengthen its ecosystem.

At the same time, analysts remain focused on the potential for artificial intelligence to drive device upgrades and services revenue.

Apple stock AAPL gained 0.75% on Thursday.

Apple and LG prepare wider smart home ecosystem

The products developed with LG will carry the South Korean company’s brand, with LG handling manufacturing and product support.

The lineup is expected to include the LG Video Doorbell Wired, Floodlight Cam, Outdoor Cam Plug-In, Indoor Cam Plug-In, Smart Deadbolt Lock, Smart Thermostat and Temperature Sensor.

The products are not expected to reach consumers for at least several months, as development has lagged behind Apple’s own devices.

LG has recently sought regulatory approvals for the products, including filings with the US Federal Communications Commission and UL Solutions.

The filings include product names, specifications, and other details, while LG has requested confidentiality for photographs and more precise information until early next year.

Many of the devices support Wi-Fi and Bluetooth, as well as Thread and Matter, smart home protocols used by Apple and other technology companies.

The smart lock also supports ultra-wideband technology, which can enable automatic unlocking when users approach a door.

The planned ecosystem would place Apple and LG in closer competition with established smart home offerings from Amazon’s Ring and Alphabet’s Google Nest.

Apple seeks to revive HomeKit with AI

Apple launched HomeKit in 2014, but the platform has gained less traction than competing smart home ecosystems from Amazon and Google.

The new devices are part of a broader effort to reboot Apple’s smart home strategy.

Apple is also planning additional products, including a privacy-focused home monitoring device, a smart home hub with a screen attached to a robotic arm, and an in-home security monitoring service.

The company is expected to use Siri and AI as part of this strategy.

The push also comes as Apple explores ways to integrate AI across its broader product ecosystem.

Dan Ives, an analyst at Wedbush, said Apple’s AI strategy could add about $75 per share to the company’s valuation as AI helps drive device upgrades and increase services revenue.

“Apple is moving into a new stage of its ecosystem story,” Ives said, adding that AI could eventually account for more than 15% of Services revenue.

Ives has an Outperform rating on Apple with a $400 price target.

He expects the iPhone 18 upgrade cycle to support the company over the next several quarters, noting that about 375 million iPhones have not been upgraded in more than four years.

He also expects Apple’s foldable iPhone Duo to generate additional demand, estimating sales of about 10 million units over the next few quarters.

Citi remains bullish ahead of Apple earnings

Citi has also reiterated its Buy rating on Apple ahead of the company’s earnings expected in early November.

The bank said investor attention this quarter is likely to centre on Services growth momentum, alongside continued weakness in App Store revenue and concerns about the potential impact of agentic AI.

Citi also pointed to gross margin pressure from higher memory costs, partly offset by higher average selling prices, as well as iPhone sales seasonality following the lack of a base-model launch this autumn.

The combination of the smart home expansion, AI strategy, and upcoming iPhone upgrade cycle gives investors several areas to watch as Apple approaches its next earnings report.

The post Apple stock rises as smart home push and AI strategy draw investor focus appeared first on Invezz

US stocks ended mixed on Thursday, with the Nasdaq Composite posting its steepest decline among the major indexes as artificial intelligence stocks came under pressure and rising oil prices added to inflation concerns.

The Nasdaq fell 1.24% to 27,197.10 points, while the S&P 500 lost 0.46% to 7,765.70. The Dow Jones Industrial Average gained 0.09% to 51,225.48.

AI stocks fall after OpenAI revenue report

Technology and semiconductor stocks declined after a Financial Times report said OpenAI’s annualised revenue was about $20 billion below the figure the company had previously signalled.

Oracle shares fell more than 5%, while Nvidia and Advanced Micro Devices declined about 2% and 3%, respectively.

Semiconductor stocks were among the weakest performers after having gained more than 80% so far this year.

The report added to concerns around the large capital requirements of the AI industry.

Broadcom and Oracle also faced pressure after reports that Broadcom was arranging $50 billion in financing for OpenAI, while Oracle was seeking additional funding.

Investors are also looking ahead to the third-quarter earnings season, which begins next week.

Palantir was among the few technology stocks to gain, rising 2% after Goldman Sachs upgraded the company to Buy from Neutral.

The firm said the company could benefit from increasing demand for sovereign AI and customised applications.

Oil prices rise as Middle East tensions persist

Oil prices climbed as concerns over supply disruptions in the Middle East continued to weigh on markets.

Brent crude settled 3.6% higher, while West Texas Intermediate gained 3.19%.

Oil prices were supported by attacks on shipping in the Strait of Hormuz and a reduction in US oil production linked to hurricane activity.

US crude prices have risen more than 60% this year as the conflict involving Iran has tightened global supplies. Higher energy prices have also increased concerns that inflation could remain elevated.

President Donald Trump later said the US would not attack Iran before the midterm elections, helping oil prices retreat from their session highs.

Treasury yields remain elevated

Treasury yields remained close to multi-year highs as investors assessed the impact of higher oil prices on inflation and the Federal Reserve’s interest-rate outlook.

The benchmark 10-year Treasury yield was last down more than 7 basis points at 5.22%, while the 30-year yield fell 13 basis points to 5.60%.

The moves followed a strong auction of 30-year Treasury bonds.

The rise in yields has added to volatility in equities, particularly as investors assess whether higher energy prices could keep inflation elevated and lead to further interest-rate increases.

Markets currently expect the Federal Reserve to leave rates unchanged this month, while the probability of a December rate hike is nearly 70%, according to CME’s FedWatch tool.

Fed Governor Christopher Waller has said further rate increases will probably be necessary, although the timing remains flexible.

Other stocks move on company news

Outside the technology sector, PepsiCo shares gained after the company said it would pursue additional spending cuts while lowering its annual core profit forecast.

Starbucks shares edged lower following reports that the coffee chain was exploring a potential acquisition of Chipotle Mexican Grill. Chipotle shares jumped on the report.

The post Dow holds steady as Nasdaq falls 1.24% on AI stocks, oil surge appeared first on Invezz

Anglo American is issuing a stark warning to European antitrust regulators, claiming it will be forced to shutter its Brazilian nickel operations if a proposed sale to Hong Kong based MMG Ltd is blocked. The half billion dollar deal has become entangled in a rigorous Phase II review by the European Commission, driven by concerns that shifting ownership could allow critical mineral supplies to be diverted away from European stainless steel manufacturers. This tension reflects a broader strategic anxiety within the EU regarding its heavy dependence on Chinese interests for essential battery and industrial metals.

Executives at Anglo American are arguing that blocking the acquisition will not actually secure Europe’s supply chain but will instead lead to the total loss of the asset. Ruben Fernandes, the company’s CEO in Brazil, has indicated that there is no alternative buyer on the horizon. He maintains that since the firm committed to exiting the nickel sector over two years ago, any prohibition of the sale would leave them with no choice but to place the mines into care and maintenance, effectively paving the way for permanent closure.

The stakes involve several key assets including the Barro Alto and Codemin ferronickel operations along with promising development projects at Jacaré and Morro Sem Boné. These sites contributed nearly forty thousand metric tons of nickel last year alone. Under the current terms, MMG would provide an upfront cash payment of three hundred fifty million dollars, supplemented by performance linked payouts totaling another one hundred fifty million dollars.

As representatives from both companies gather in Brussels to defend the merger, they have extended the deal’s deadline to October 2026. Despite this extra breathing room, the immediate survival of these mining operations remains precariously dependent on whether European officials prioritize geopolitical supply security over the commercial viability of a global mining giant’s divestment strategy.

Mining giant BHP has reached an agreement to sell its Kambalda Nickel Concentrator and several accompanying tenements to South African firm Gold Fields. The deal carves out a significant piece of infrastructure from BHP’s currently suspended nickel operations in Western Australia, transferring both the processing facility and related mineralization rights. While the transition is expected to be finalized by 2027 pending regulatory approval, BHP will maintain management of the site until the handover is complete.

For those working at the facility, the move offers a glimmer of stability. Gold Fields intends to assess how best to utilize the concentrator over the long term and has committed to offering employment to staff who directly support the asset. Annabelle Blom, BHP’s Vice President for WA Nickel, described the sale as a positive result that brings much needed certainty to employees and the wider Goldfields community, noting that Gold Fields is a respected operator with deep roots in the region.

Despite this divestment, the future of BHP’s remaining nickel assets in Western Australia stays uncertain. Those operations remain suspended as the company prepares for a comprehensive review by February 2027. Depending on market conditions and internal evaluations, BHP may decide to sell off more assets, keep them dormant, attempt an operational restart, or shut them down permanently.

The acquisition comes at a transitional moment for Gold Fields following a high profile setback in the Australian market. Just recently, Northern Star Resources flatly rejected an unsolicited twenty seven billion dollar takeover bid from Gold Fields. Northern Star’s leadership claimed the offer significantly undervalued their portfolio during a critical growth phase, describing the attempt as opportunistic given their current operational milestones.

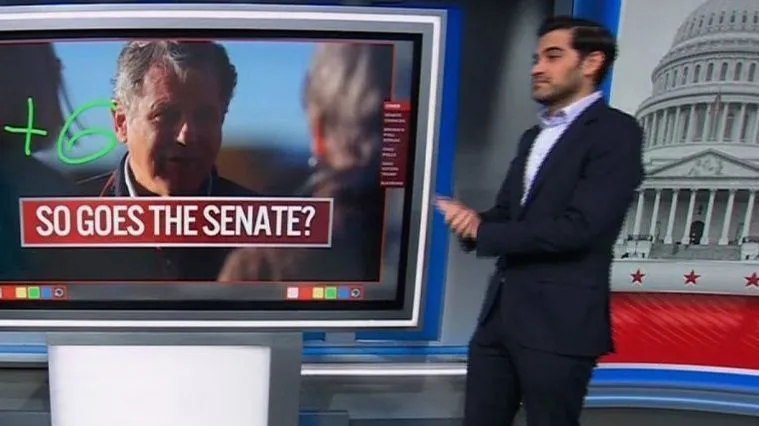
The political landscape in Ohio is experiencing a sudden and dramatic transformation as prediction markets begin to favor a Democratic victory in the upcoming Senate race. This unexpected surge comes as analysts observe a significant departure from recent electoral patterns. For years, Republicans have consistently outperformed their polling numbers in Ohio, turning what looked like competitive races into comfortable wins, but current data suggests that trend may finally be breaking.

Much of this volatility seems tied to the fluctuating popularity of Donald Trump within the state. Not long ago, Trump enjoyed a commanding double digit lead among Ohio voters during the 2024 cycle. However, that momentum has evaporated completely, with recent metrics showing his approval rating has plummeted into negative territory. This collapse provides a critical opening for Democrats who are hoping to capitalize on voter dissatisfaction.

As John Berman and Harry Enten noted in a recent analysis for CNN, the contrast between historical Republican strength and these new projections creates an unpredictable environment. While prediction markets are often volatile, they currently signal a level of confidence in a Democratic flip that hasn’t been seen in several cycles. Whether this represents a permanent realignment or a temporary dip remains to be seen as candidates scramble to secure the middle ground.

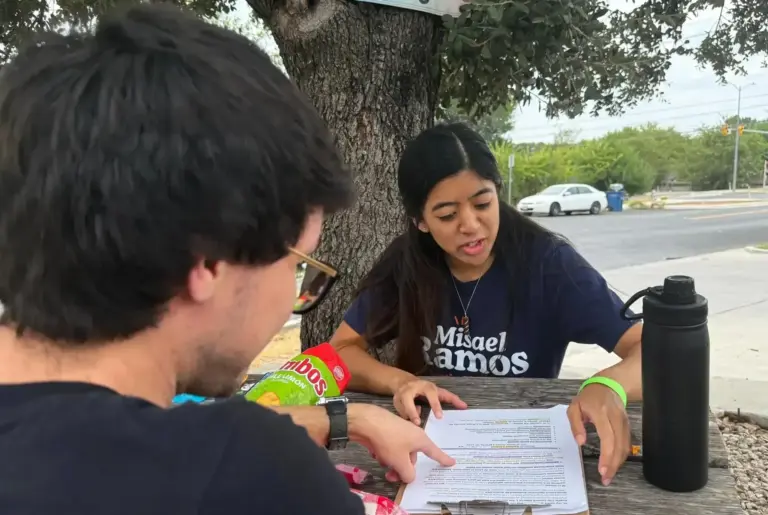
Inside a cavernous church sanctuary in Austin, the energy feels less like a traditional political rally and more like a community workshop. Members of the Democratic Socialists of America gather not just to debate high-level theory, but to receive practical training on filming immigration enforcement actions and coordinating boycotts to support barista contracts. This blend of immediate mutual aid and long-term ideological striving defines the local chapter, where making hundreds of sandwiches for the hungry is viewed as being just as essential as campaigning for systemic overhaul.

For newcomers like Mark Ramirez, a software engineer who grew tired of doomscrolling through global crises, the organization offers an active alternative to despair. While he views the mainstream Democratic Party as too entwined with corporate interests, he sees the DSA as a vehicle for tangible resistance. By tracking ICE raids and fighting against automated license plate readers, members attempt to bridge the gap between utopian goals—such as universal healthcare and abolished prisons—and the gritty reality of municipal politics.

This localized effort mirrors a wider surge in democratic socialism across the United States, with national membership doubling recently to 126,000. In Austin, this momentum is embodied by candidates like Misael Ramos, who runs for City Council by translating radical platforms into concrete policy proposals, such as repurposing city land for affordable housing. Despite facing arrests during protests and accusations of promoting communism from Republican critics, proponents argue that their strength lies in sweat equity rather than campaign contributions.

As polls show an increasing number of Americans drifting away from capitalism and toward socialist ideals, the tension within the Democratic coalition continues to grow. While party leadership often worries that radical rhetoric might alienate moderate voters, activists in Austin believe that building power from the bottom up is the only way forward. To them, every door knocked and every sandwich delivered is a small step toward rebuilding society into what they describe as a real democracy.

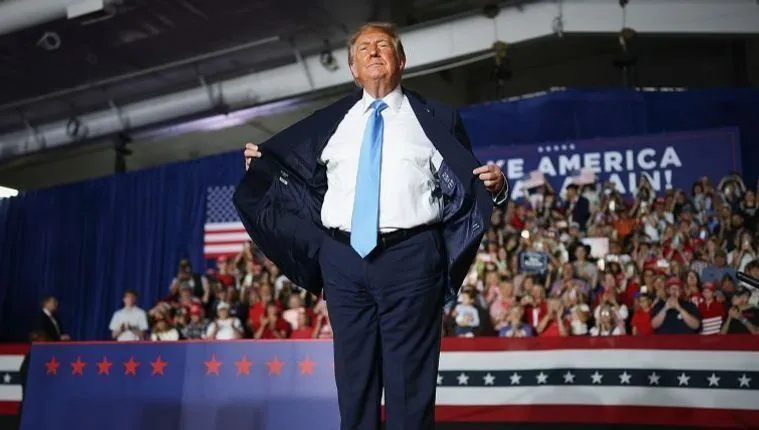
In the world of high stakes politics, fashion is often dismissed as trivial, yet for a man whose entire public persona is built on the image of extreme wealth, a stray clothing tag can become a loud statement. Former President Donald Trump was recently captured in photographs sporting a suit from Jos. A. Bank, a mid tier brand far removed from the bespoke luxury usually associated with his lifestyle. For someone who promotes hundred thousand dollar watches and adorns his properties in gold leaf and Corinthian marble, the sight of a budget friendly blazer feels fundamentally out of character.

The discrepancy becomes even more awkward when considering the political messaging involved. While the garment appears to be part of a wrinkle resistant collection retailing for under three hundred dollars, it was likely manufactured overseas in China or Bangladesh. This stands in stark contrast to Trump’s frequent promises to revitalize American manufacturing and bring industry back to U.S. shores. While he sells American made ties through his online store, the actual fabric covering his shoulders seems to tell a different story about global supply chains.

Some observers might speculate that this was a calculated move designed to make him seem more relatable to everyday Americans facing an affordability crisis, similar to how other politicians have used casual wear to signal commonality with voters. However, given that the tag became visible while he was dancing onstage, it seems less like a strategic branding exercise and more like a simple wardrobe oversight. When paired with reports that he purchased relatively inexpensive Florsheim shoes for his cabinet members, it suggests that his taste in attire may simply be shifting away from the elite Italian labels like Brioni that defined his early television career.

Ultimately, whether this shift toward affordable workwear is accidental or intentional, it remains an odd footnote for a man obsessed with status symbols. From luxury jets provided by foreign governments to massive ballrooms funded by donors, Trump has spent decades cultivating an aura of opulence. Yet regardless of whether he wears a tailored masterpiece or a discounted mall suit, the most enduring piece of clothing associated with his movement remains the fifty five dollar red cap that serves as the ultimate symbol of his populist appeal.