Author

admin

Browsing

The cornerstone of American democracy rests on the belief that informed citizens use reason and logic to navigate the complexities of governance. However, a recent study conducted by social scientists at UC Berkeley suggests that this ideal is far from reality. Rather than carefully weighing multiple variables when faced with difficult political decisions, most Americans rely on mental shortcuts, focusing on a single priority while ignoring almost everything else.

Researchers Kirk Bansak and Nidhi Banavar explored how people make choices regarding sensitive topics such as immigration, climate change, and the selection of political candidates. In one exercise, participants were asked to choose between fictional Senate candidates based on several attributes including age, race, education, and military experience. Instead of analyzing the full profile of each candidate, many participants based their entire decision on just one specific factor that mattered most to them personally.

This tendency toward simplification does not necessarily mean that voters are acting irrationally. According to Banavar, human brains are simply not built like infinite computational machines capable of processing every possible variable in a complex equation. While some individuals do conduct a thorough analysis or a balanced tally of pros and cons, the majority opt for the path of least resistance to reach a conclusion quickly.

These findings have significant implications for how political campaigns communicate with the public. If policymakers know that a vast segment of the population makes decisions based on a single issue—such as immediate financial costs in the case of climate change—they may tailor their messaging to highlight that lone factor while omitting broader scientific or systemic contexts. This creates a feedback loop where complex issues are reduced to slogans because it aligns with how the human mind naturally filters information.

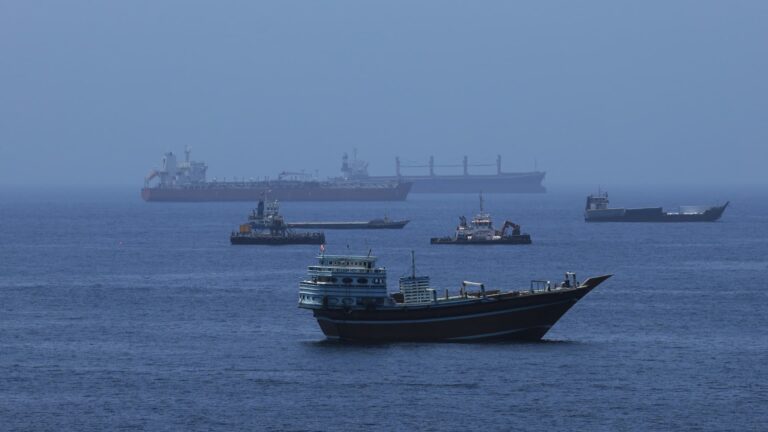
Global energy markets reached a significant milestone this week as crude oil flows through the Strait of Hormuz finally returned to prewar levels. Data from Goldman Sachs, JPMorgan, and Kpler indicate that exports moving through this critical maritime chokepoint have averaged about 13.5 million barrels per day over the last week, effectively hitting the previous baseline. While the restoration of these volumes suggests a return to stability in raw crude transport, the recovery has not translated into relief for consumers at the pump.

Despite the steady flow of crude, the global economy continues to struggle with severe constraints in refined product supplies. This imbalance has pushed diesel prices to record highs, creating persistent inflationary pressure across various sectors. The situation has become so acute that President Donald Trump is reportedly weighing a ban on diesel exports in an attempt to force more fuel into domestic markets and drive down costs for American drivers and businesses. In early trading Thursday, both Brent and WTI crude futures trended lower as traders balanced these logistical gains against broader economic anxieties.

The timing of this energy shift coincides with the start of the fourth quarter, which opens amidst lingering volatility in the bond market. Global equities remain sensitive to elevated Treasury yields even after a slightly softer inflation reading in the United States showed August PCE rising by 3.4 percent. Minneapolis Fed President Neel Kashkari emphasized that inflation remains stubbornly high after five years of elevation, suggesting that recent data does little to change the central bank’s cautious outlook on interest rates.

Beyond energy and economics, the technology sector continues its rapid evolution with Google unveiling Gemini 4 Argon, its most sophisticated AI model focused on cybersecurity and coding. This comes as Meta celebrates its strongest monthly performance since 2022, fueled by investor enthusiasm for its new Muse personal AI agent. Meanwhile, political scrutiny is turning toward Commerce Secretary Howard Lutnick following financial disclosures revealing he earned over 250 million dollars last year, largely through distributions from his former firm, Cantor Fitzgerald.

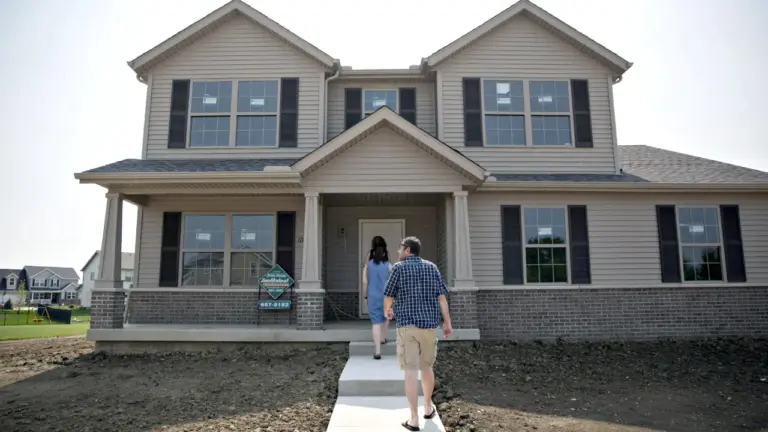
Prospective homebuyers are facing a steeper climb as mortgage rates hit their highest mark since late 2023. According to the latest Primary Mortgage Market Survey from Freddie Mac, the average rate for a benchmark 30 year fixed mortgage jumped to 7.28 percent this week, up from 7.03 percent just seven days prior. This represents a significant leap compared to where things stood a year ago, when the average rate sat at 6.34 percent. Shorter term options aren’t faring much better, with the average 15 year fixed mortgage climbing to 6.6 percent.

While many people associate these shifts with direct actions from the Federal Reserve, experts note that mortgage rates actually track more closely with the 10 year Treasury yield, which recently hovered around 5.23 percent. These fluctuations are often driven by a complex mix of geopolitical tensions and broader economic indicators. Despite the volatility, Freddie Mac chief economist Sam Khater suggested that overall favorable economic conditions continue to provide some baseline support for the housing market.

However, the real world impact on family budgets is becoming harder to ignore. Hannah Jones, a senior economist at Realtor.com, pointed out that because rates have risen nearly a full percentage point over the last year, monthly payments on a median priced home have increased by more than 200 dollars in principal and interest alone. This comes even as some median home prices have dipped slightly over the same period, effectively neutralizing any potential savings for new buyers.

For those still determined to enter the market, professionals suggest focusing on personal financial health rather than trying to time the peaks and valleys of national trends. Because final rates vary wildly based on credit scores and down payments, two different borrowers could see an entire percentage point of difference regardless of what the headlines say. Experts advise buyers to rate proof their budgets now to ensure they can handle future swings without compromising their financial stability.

Nike shares dipped further in extended trading on Thursday after the sportswear giant missed revenue expectations and revealed a deepening crisis in one of its most critical markets. While earnings per share actually beat analyst predictions, coming in at 48 cents against an expected 43 cents, total revenue fell four percent to 11.21 billion dollars. This slight miss underscores a broader struggle for the company as it grapples with shifting consumer habits and stubborn economic headwinds.

The primary driver behind the disappointing numbers was a staggering collapse in China, where revenues plunged by 26 percent. This continued slump reflects a volatile environment characterized by geopolitical tension and decreased consumer spending power. Although performance in North America remained relatively stable, barely exceeding estimates at 5.13 billion dollars, it wasn’t enough to offset the bleeding in Asia or soothe investors who have already seen Nike’s stock plummet more than 40 percent so far this year.

In response to these challenges, CEO Elliott Hill announced a sweeping reorganization aimed at positioning the brand for long term growth. The plan involves modernizing the supply chain, expanding operations into India, and streamlining how the global workforce is organized. However, this strategic shift comes with a human cost; Hill admitted in a letter to employees that the changes would lead to layoffs starting in 2027, acknowledging the uncertainty such news brings to the staff.

Financial analysts see this restructuring as a necessary but painful step toward efficiency, with Nike projecting about 2.5 billion dollars in savings through fiscal 2031. Despite these hopes for future lean operations, the immediate outlook remains bleak. The company warned that overall revenues are expected to decline by a high single digit percentage throughout fiscal 2027 as it continues to fight for footing amidst rising inflation and intense competition globally.

Most people imagine their lives changing instantly if they stumbled upon a small fortune, but for one Texas man, finding over 128 thousand dollars atop an ATM was simply a problem that needed solving. The thirty seven year old barber was visiting a Bank of America machine in Lewisville, about thirty miles north of Dallas, when he and a companion noticed two bags resting on the equipment. One contained nineteen checks, while the other held a staggering sum of cash totaling exactly 128,514 dollars.

Rather than walking away with the windfall, the man immediately began searching for the rightful owner. After noticing information on one of the bags that seemed to link the money to a nearby Chick fil A, he drove straight to the restaurant to see if it belonged there. When a manager informed him that the money did not belong to the business, he didn’t hesitate to call 911 so that law enforcement could secure the funds and track down whoever had lost them.

An investigation later revealed that the money actually belonged to Bank of America and had been handled by its cash vendor, Brinks. Police believe a technician servicing the ATM likely forgot the bag on top of the machine after finishing their work. Officers verified the total using a digital currency counter and confirmed that every single cent was accounted for, noting there was no evidence that any of the funds were tied to criminal activity.

Local authorities say they have rarely encountered such honesty given the scale of the find. Detective Gina Miller mentioned she has dealt with returned wallets and IDs throughout her career but had never seen anyone turn in this much cash. Police Chief Brook Rollins praised the man for his decisive action, stating that he didnt even blink before trying to return the money. While keeping it could have led to felony theft charges, the man sought neither rewards nor publicity, though he has agreed to attend a private ceremony honoring his integrity.

Ynon Kreiz is stepping into his new role as Co-CEO of the combined entity formed by the merger of Paramount and Warner Bros. Discovery with a paycheck that reflects the massive scale of the deal. According to a recent SEC filing, the sixty-one year old executive will see his first-year compensation soar to more than 46.5 million dollars. This represents a significant leap from his time leading Mattel, where his total compensation for 2025 was roughly 15.1 million dollars.

The bulk of this windfall comes from a substantial signing incentive consisting of restricted stock units valued at 31.5 million dollars. Beyond the initial sign-on bonus, Kreiz’s basic terms include an annual base salary of 5 million dollars and eligibility for a yearly performance bonus targeted at nearly 5 million dollars. He is also slated to receive 1.25 million shares of Class B common stock as part of a pre-closing award, further tying his financial success to the health of the newly merged media giant.

As David Ellison’s primary partner in managing the consolidated organization, Kreiz begins his tenure on October 5, just twenty four hours before the anticipated closing of the staggering 111 billion dollar merger. The company has yet to announce an official name for the joined venture, but it is already making waves with these high-level leadership investments. Following the merger’s completion, Kreiz will be eligible for additional grants totaling up to 5.1 million dollars shortly after closing, followed by another equity award of about 20 million dollars on his first anniversary.

To ensure long term stability during this transition, most of these stock awards are structured with specific strings attached. With the exception of the immediate signing reward, those equity grants will vest in equal quarterly installments over a three year window. This means Kreiz must remain employed with the firm through those dates to fully realize the gains, aligning his personal wealth with the successful integration of two entertainment titans into one singular powerhouse.

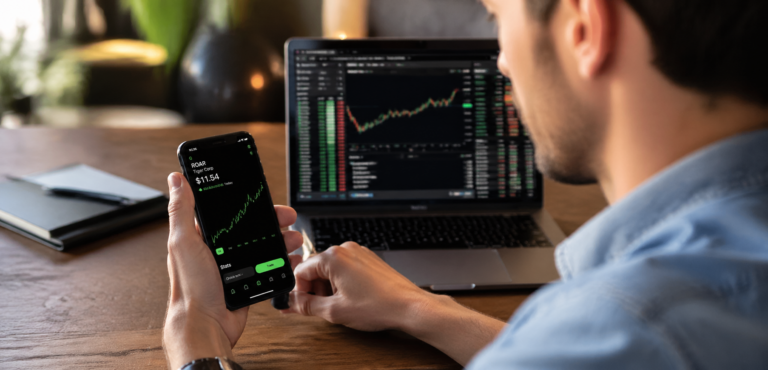
Robinhood (HOOD) unveiled a sweeping set of features for active traders at its annual summit in Houston.

The headline addition is fully integrated “agentic trading,” allowing AI algorithms to make trades autonomously on behalf of users.

Coupled with new “24/7 weekend stock trading”, prediction contracts on corporate KPIs, and US perpetual futures, Robinhood is doubling down on high-frequency, institutional-style functionality for retail investors.

Addressing an audience about 3x larger than last year’s event, CEO Vlad Tenev highlighted the brokerage’s commitment to giving its 28 million users an edge.

Robinhood stock is currently up some 75% versus its year-to-date low.

What we know about Robinhood’s new offerings

Robinhood’s new native AI feature simplifies automated strategies by bringing agentic trading into its main app.

Previously, over 150,000 clients had to manually connect external models – like Claude or Codex – to their brokerage accounts.

To address security and “hallucination” concerns, Tenev emphasized built-in safeguards in a CNBC interview today.

By default, trade approvals remain toggled on, and agents run in isolated sandbox accounts. “You can name your agent… and you have to decide that you want to move funds,” he explained.

Parallel to AI tools, Robinhood launched round-the-clock weekend equity trading.

This structural shift allows investors to immediately react to breaking Saturday and Sunday news rather than waiting for Sunday evening futures opens.

What AI agents and 24/7 trading mean for HOOD shares

For investors, Robinhood’s new features mark an aggressive play to “capture market share” from traditional brokerages.

Management expects the expanding suite to prove a major driver of future revenue.

Offering higher-velocity instruments, including “crypto perpetual futures” and earnings prediction contracts, creates recurring fee streams and deeper customer engagement.

While institutional-grade features carry regulatory scrutiny and execution risk, expanding into “living hours” stock access solidifies Robinhood’s monetization roadmap.

If retail adoption scales as intended, increased trading volume could provide sustained momentum for HOOD shares outlook.

Should you invest in Robinhood stock today?

As financial technology ventures into autonomous AI executions, Robinhood Markets’ deliberate risk management remains central to its pitch.

By siloing AI agents inside dedicated secondary accounts, the platform prevents automated algorithms from risking core balances or long-term retirement portfolios.

Users maintain granular control, deciding whether to auto-approve trades or review every order in real time.

“We want people to feel like they’re at a disadvantage when using any other trading platform,” CEO Vlad Tenev noted, framing safety as an enabler rather than a barrier.

Combined with zero-data-retention agreements with AI labs, Robinhood aims to set a retail benchmark for secure, algorithmically driven investing.

Note that Wall Street analysts currently rate Robinhood shares at Overweight – with price targets going as high as $170, indicating potential for significant further gains from here.

The post Robinhood commits to giving traders an edge with 2 new features appeared first on Invezz

Microsoft shares MSFT rose about 2% on Wednesday after Piper Sandler raised its price target on the software giant to $610 from $550 while maintaining an Overweight rating.

The new target represents nearly 18% upside from the stock’s current trading level and reflects higher estimates and an expanded enterprise value-to-operating cash flow multiple, as the brokerage grows more confident in the outlook for Microsoft’s Microsoft 365 commercial cloud business.

The stock also benefited from broader market gains after fresh US economic data showed inflation slowing last month, pushing Treasury yields lower.

The S&P 500 rose about 0.5%, while the Nasdaq gained roughly 1%.

M365 cloud becomes a bigger AI revenue opportunity

Piper Sandler introduced a new framework for analyzing Microsoft’s M365 Commercial Cloud business following the company’s “Super App” announcement, the rollout of its new E7 tier, and increasing adoption of consumption-based pricing for Copilot and Cowork.

The brokerage estimates that every 10% shift in customer seats from the existing E5 tier to E7 could generate roughly $2 billion in annualized revenue uplift.

The immediate contribution is expected to be limited, however, as customers gradually migrate across Microsoft’s subscription tiers.

Piper Sandler also sees a significant opportunity from consumption-based revenue generated by Copilot and Cowork.

The firm estimates that these businesses could reach a $2 billion annualized revenue run rate by the end of fiscal 2028.

The analyst said the value proposition of Copilot and Cowork is partly based on Microsoft’s ability to use its enterprise technology “harness” and auto-routing capabilities to perform tasks at lower costs than relying exclusively on frontier AI models.

That could allow Microsoft to generate revenue from AI consumption at a faster pace than the traditional seat-based Copilot model.

The opportunity is particularly important as investors increasingly focus on whether technology companies can translate heavy AI investment into sustainable revenue and cash flow.

Analysts see stronger Azure and Copilot growth

Piper Sandler’s bullish view follows a similar shift in sentiment from other Wall Street analysts.

Last week, Stifel upgraded Microsoft to Buy from Hold and raised its price target to $575 from $530, citing growing confidence that the company can sustain revenue growth in the mid-to-upper teens.

Analysts led by Brad Reback said Microsoft had “clearly turned the corner post the June quarter print,” pointing to continued strength in Azure, lower large-language-model research intensity and a growing contribution from OpenAI.

Stifel expects Azure to benefit from another 200 to 300 basis points of upside as Microsoft improves efficiency across its technology stack, including silicon, models and software.

The analysts also pointed to comments from Chief Financial Officer Amy Hood that Microsoft had reduced “dock-to-live times” — the period between hardware coming online and becoming ready to generate revenue — by more than 50% over the past year.

That improvement could allow Microsoft to convert additional infrastructure capacity into revenue more quickly.

Copilot adoption adds another growth lever

Microsoft’s AI monetization story is also expanding beyond Azure.

Copilot’s seat count reached roughly 30 million in the fourth quarter, an increase of 10 million from the previous quarter.

Meanwhile, GitHub’s move toward consumption-based pricing provides another potential source of revenue growth.

Stifel expects these factors to offset moderating seat growth as Microsoft 365 approaches 500 million seats, allowing the company to sustain at least mid-teens growth for several years.

The brokerage also said its previous concerns about margin compression had proved “too negative.”

Azure efficiency gains, the elimination of revenue-share payments to OpenAI following an April contract revision, and Microsoft’s decision to extend the useful life of certain assets to 25 years from 15 years have all helped improve the margin outlook, according to Stifel.

The broader analyst community has also become more constructive.

Seventeen analysts have recently raised their earnings estimates for Microsoft for the upcoming period.

Microsoft shares head for strongest quarter in decades

Microsoft shares have risen about 10% this year, but the bulk of the recovery has come in the third quarter, with the stock up 36.4% so far.

That puts Microsoft on track for its strongest quarterly performance since the first quarter of 1998, when the shares gained 38.5%, according to Dow Jones Market Data.

The scale of the recent rebound partly reflects how sharply the stock had fallen at the start of the year.

Microsoft shares plunged 23.5% in the first quarter, marking their worst quarterly performance since the 2008-09 financial crisis.

Investors have since placed greater emphasis on the different parts of Microsoft’s business that can benefit from the AI boom.

StoneX analyst Yi Fu Lee said Microsoft has increasingly benefited from a “flight to quality” as investors seek technology companies with clearer paths to monetizing AI.

Investors have come to view Microsoft as “one of the highest-quality platforms in technology,” Lee said, according to MarketWatch.

StoneX reiterated a Buy rating on the stock.

Microsoft shifts focus from AI models to enterprise platforms

Lee said Wall Street’s focus has increasingly moved away from identifying which company has the strongest AI model and toward determining which companies control the enterprise infrastructure, data and systems where AI applications operate.

Microsoft is positioned as a platform capable of hosting multiple large language models, including those developed by OpenAI and Anthropic, he said.

The company’s recent Copilot developments have further strengthened the case that Microsoft can expand AI revenue beyond traditional software subscriptions.

“Microsoft is evolving Copilot from a productivity assistant into a broader enterprise AI platform,” Lee said, pointing to its capabilities across Home, Microsoft’s subscription offering for individuals and families; Code, its coding tool; and Autopilot, a personal AI assistant.

Tigress Financial analyst Ivan Feinseth similarly said Microsoft’s rally “reflects a meaningful improvement in the evidence behind [Microsoft’s] AI investment case.”

The post Why is Microsoft stock up 2% on Wednesday? appeared first on Invezz
Nike (NKE) shares have been a major disappointment for investors in 2026, but the options market believes the company’s upcoming earnings on October 1 is unlikely to offer any significant relief.

Consensus is for NKE to post $0.44 a share of earnings (EPS) on $11.34 billion in revenue, which would represent a year-over-year “decline” across both metrics.

Versus the start of this year, Nike stock is currently down an alarming 80%.

Where options data suggests Nike stock is headed

Despite NKE shares’ massive 2026 underperformance, and CEO Elliott Hill’s turnaround efforts, the derivatives market believes they will inch lower after the quarterly print.

The put-to-call ratio on options contracts expiring October 9 sits at 1.16 as of writing, indicating a bearish skew (a reading above 1.00 is typically interpreted as bearish).

And the lower price on those contracts – according to Barchart’s data – is set at $32.91 currently, signaling the footwear giant could lose another 7.74% through the end of next week.

Crucially, the technical setup heading into the earnings even also reinforces the negative sentiment.

Nike is currently trading firmly below its major moving averages (MAs), with an RSI in the mid-30s pointing to significant selling pressure that may drive its stock price lower in the final quarter of 2026.  

Why derivatives market is bearish on NKE shares

Options market is pricing in potential weakness in Nike shares because of “persistent” fundamental headwinds that continue to squeeze Nike’s bottom line.

Revenue growth remains stifled by sluggish foot traffic in key international markets – particularly Greater China – alongside weakening global discretionary spending.

Compounding these struggles is margin compression due to aggressive promotional discounting to clear out excess, stale inventory.

Additionally, higher freight expenses, supply chain friction, and stiff competition from agile rivals that are hurting adoption of new line-ups continue to eat into operating margins.

With full-turnaround initiatives under CEO Elliott Hill still early in execution, option traders signal skepticism that the upcoming quarterly print can reverse these entrenched structural hurdles.

What would determine Nike’s future trajectory

Beyond the headline revenue and earnings figures, the trajectory of Nike stock hinges on forward-looking commentary regarding inventory normalization and direct-to-consumer momentum.

Clear evidence that promotional strategies are successfully streamlining stock levels without permanently eroding gross margins will be essential to restoring investor confidence.

Additionally, Wall Street will scrutinize management’s updates on wholesale channel partnerships and product innovation cycles aimed at reclaiming market share.

While near-term derivative positioning reflects caution, any tangible progress on supply chain efficiency or signs of stabilizing wholesale demand could provide the foundation needed for the stock to base and potentially initiate a long-term recovery.

Heading into Q1 earnings, Wall Street rates NKE stock at Hold with a mean price target of about $44.57.

The post Nike stock seen sinking further after Q1 earnings: find out more appeared first on Invezz

Meta Platforms META shares were under pressure on Wednesday even as broader US markets moved higher, as investors weighed the potential threat from OpenAI’s newly launched Dots AI agent to the social media giant’s fast-growing Muse platform.

The stock started the session down by almost 2%, but picked up later in the day, and was down 0.2% in afternoon trading.

The stock has gained more than 28% over the past month, helped by enthusiasm around Muse, which has emerged as a key part of Meta’s consumer artificial intelligence strategy.

But the launch of Dots has prompted investors to reassess whether Meta can maintain its early lead in the increasingly competitive AI agent market.

At the same time, StoneX analyst Mark Zgutowicz warned that Meta’s muse could actually intensify concerns over the company’s enormous AI infrastructure spending rather than alleviate them, adding to investors’ worries.

OpenAI’s Dots targets premium users

OpenAI is rolling out Dots as an “always-on” AI agent app designed to compete with Meta’s Muse.

While Meta shares initially rallied on Tuesday afternoon following OpenAI’s presentation, the stock reversed course in Wednesday trading.

Investors had already anticipated greater competition for Muse after its viral launch earlier this month helped propel Meta shares more than 30% higher.

However, Evercore ISI analyst Mark Mahaney said Dots currently has a more limited distribution model than Muse.

“Importantly, unlike Meta’s Muse, Dots is not launching as a broadly available consumer product, as access is initially concentrated in premium professional and business plans,” Mahaney told clients late Tuesday.

“For now, we see Meta with Muse as the clear leader in the personal AI agent space.”

Dots is initially available to users of OpenAI’s $100-a-month Pro plan and Business Premium plans, alongside more expensive custom tiers such as Enterprise. OpenAI has said it intends to “expand to more users soon.”

By comparison, Muse offers users free access to its core capabilities, with paid plans available for heavier usage.

The app provides more than 100 million weekly AI tokens, while power users can increase their allocation through $20- and $100-a-month subscription options.

Distribution gives Meta an early advantage

Mahaney said the difference in access could play an important role in determining how quickly the two products gain users.

“We think that accessibility and massive distribution will continue to give Meta an early advantage in consumer adoption, while OpenAI’s existing relationships with businesses and professional users could help Dots gain traction in more complex and economically valuable work,” he added.

Meta is also expanding Muse beyond individual consumers.

The company unveiled Muse for Small Business on Tuesday, allowing its AI agent to connect with software from Asana, Zoom, Intuit, Box, Canva and Salesforce’s Slack.

The tool can also connect with Meta advertising accounts and professional Instagram and Facebook profiles.

Pricing remains aligned with the existing Muse offering, which is free within usage limits and available through subscriptions for higher usage.

AI spending remains a concern

Despite the enthusiasm around Muse, StoneX analyst Mark Zgutowicz warned that the product could intensify concerns over Meta’s enormous AI infrastructure spending rather than alleviate them.

Zgutowicz, who has a Hold rating on Meta, said Muse’s infrastructure requirements could put further pressure on the company’s returns.

“We…see Muse’s materially higher infrastructure-intensity adding to, not relieving pressure from, Meta’s existing ROIC debate,” he said.

Meta expects to roughly double capital expenditures to about $140 billion this year as it invests heavily to compete with other Big Tech companies in AI.

The scale of the spending has raised questions among investors over whether the investments will generate sufficient returns.

Analysts have raised Meta price targets

The launch of Muse has nevertheless prompted a wave of bullish analyst actions.

JPMorgan analysts led by Doug Anmuth raised their Meta price target to $920 from $820 earlier this month, saying Muse could become “the most widely used consumer AI application since ChatGPT.”

Citizens raised its target to $885 from $770, while KeyBanc analyst Justin Patterson lifted his target to $900 from $780.

Cantor Fitzgerald also raised its target to $860 from $680.

The series of target increases has strengthened investor expectations that Meta’s AI investments could eventually create new monetization opportunities, although the emergence of Dots highlights the competitive pressure facing the company as it expands further into AI.

The post Why is Meta stock down on Wednesday? appeared first on Invezz